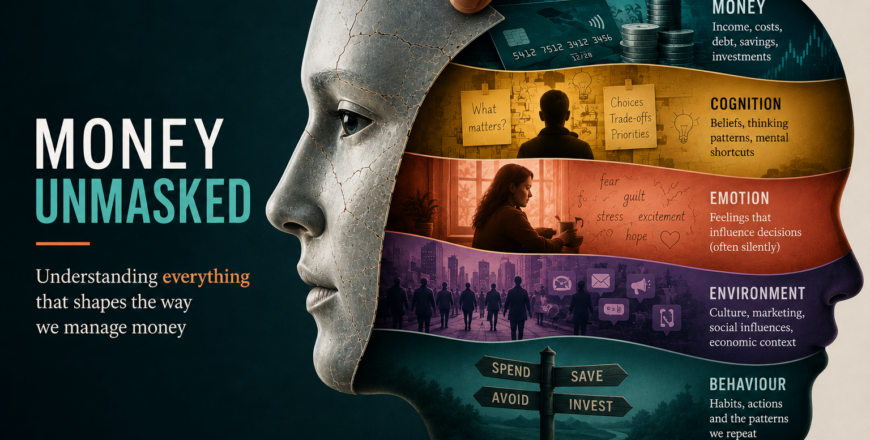
Money Unmasked


- Description
- Curriculum
- Reviews
You’ve tried the budgets. The apps. The spreadsheet you swore you’d keep up this time.
And still, the letter sits unopened until it becomes a fine. The subscription you meant to cancel renews again. The account you can’t bring yourself to check gets harder to face every week. Underneath it all is the quiet shame of starting over, again.
Most money advice was built for a brain that isn’t yours.
You are not bad with money. You’ve been handed systems that work against the way you think.
When executive function, impulsivity, sensory overwhelm and avoidance meet a money system designed for a neurotypical brain, money leaks through dozens of small, repeated decisions. That is a design problem, not a character flaw.
Money Unmasked:
The Science of Financial Behaviour for the Neurodivergent Brain
Money Unmasked is a research-informed financial wellbeing programme that helps neurodivergent adults understand their financial behaviour and build a financial system that works with the way their brain operates.
This programme is for you if:
- You’re ADHD, autistic or otherwise neurodivergent, diagnosed or self-identified
- You avoid opening bank statements or checking your balance
- You earn a reasonable income but can’t see where it goes
- You’re tired of advice that starts with “just be more disciplined”
How it works
Across 11 modules, you’ll move step by step through spending, executive function, money beliefs, debt, budgeting, earning, investing, relationships, wealth and legacy. Then you’ll bring it all together into your own Personal Financial Blueprint.
What changes
- Fewer surprise charges and missed payments
- Bills and savings that run on systems, not willpower
- Money conversations with your partner that don’t end in a shutdown
- A plan built for your brain that you’ll actually return to
Your instructors
Jouré Rustemeyer, Cognitive Facilitator and Neurodiversity Specialist with more than 20 years’ experience, founder of Help My Child and Neuro Adult Support.
Dr. Julia Myers, PharmD, MBA, TEDx speaker and founder of Generational Wisdom®.
Together, we bring neuroscience, psychology, financial behaviour and practical financial planning into one programme.
You don’t need more willpower. You need a system built for you.
Every brain deserves a money system that works with it, not against it.

-
3
 Objective for Module 1 - Why Money Feels Different
By the end of this module, you’ll understand why knowing what to do with money doesn’t always lead to doing it, and what gets in the way.
-
4
Part 1 — Why Knowing Isn't Enough
Before we can change the way we manage money, we need to understand what actually shapes our financial behaviour. This module looks beyond budgeting and financial knowledge to explore the interaction between money, cognition, emotion, motivation, behaviour and the environment around us. It examines executive functioning, reward and decision-making, stress, emotional regulation, neurodivergence and the financial systems we operate within. Most importantly, it introduces a different way of looking at financial difficulties: not as personal failure, but as the result of an interaction between the person, the task and the environment.
-
5
Part 2 - Reward, Motivation and the Environment
Why can something feel important and still lose out to something else? This lesson looks at how rewards capture attention, why future rewards lose value the longer we have to wait for them, and why importance and motivation are not the same thing. It also examines how the consumer environment is designed to make immediate rewards more compelling, and why these patterns affect everyone, not only people with ADHD.
-
6
Part 3 - Stress, Emotion and Financial Behaviour
Why do we sometimes act against our own financial interests, even when we know better? This lesson examines how stress changes the conditions under which financial decisions are made, how emotions shape the questions we ask ourselves, and why a financially unhelpful behaviour, such as spending, gambling or avoidance, can still serve a psychological function.
-
7
Part 4 - Neurodivergence and Susceptibility
What does research actually tell us about neurodivergence and money, and what does it not? This lesson distinguishes established evidence from reasonable inference across ADHD, autism, dyslexia and other profiles, and introduces the idea of susceptibility: the financial vulnerabilities discussed in this module are human ones, but people differ in how strongly particular demands affect them.
-
8
Bonus - Between Knowing and Doing: Your Module 1 Toolkit
Knowing what to do with money isn’t the same as being able to do it consistently. These worksheets help you find out what sits in between for you: the strengths you already have, the parts of managing money that ask the most of you, and what a behaviour might be doing for you. They are a starting point for asking “What is making this difficult for me?” instead of “Why am I bad with money?”
-
9
 Module 1 - Knowledge CheckTen questions to check your understanding of the key ideas in Module 1: what financial literacy includes, how executive functions and reward affect money, why avoidance keeps happening, and why the same money problem can have different causes. It isn't a test of how good you are with money. The answers, with explanations, are on the last page.
-
10
Objective for Module 2 - Your Financial Story
By the end of this module, you’ll be able to trace where your beliefs about money came from and how they shape your decisions today.
-
11
Part 1 - Start With Your Roots
Before we ever open a banking app or decide whether to buy something, we are already carrying beliefs about money, most of which we did not choose. This lesson explores where those beliefs come from: the four financial influences, the money messages we heard and the ones we caught, and the money scripts that run quietly in the background of adult decisions. It also looks at what happens when a functional difficulty is explained as a character flaw, why many neurodivergent adults mask their money struggles, and what our money story may have given us that is worth keeping.
-
12
Part 2 - Rewriting The Story
Understanding your money story is the first step. Changing it is the next. In this part, we separate net worth from self-worth, look at scarcity and what "enough" means, and sort what you were handed into what you want to keep, change, stop and start. Then you'll turn one old belief into one small, practical change.
-
13
Bonus - Unpacking the Backpack: Your Module 2 Toolkit
Most of the beliefs we carry about money were packed for us long before we had any say. These exercises help you open the backpack, see where your money beliefs came from, and decide what stays and what goes. Your money story can be your limit or your leverage. These tools help you choose which.
-
14
Module 2 - Knowledge Check
-
15
Objective for Module 3 – Understanding Impulse Spending
By the end of this module, you’ll understand what drives an impulse purchase, from anticipation and attention to stress and tiredness, and how to change the pattern.
-
16
Part 1 - What Happens Before a Purchase
Before we can change our spending, we need to understand what happens between noticing something and paying for it. This part explores impulse buying, reward and anticipation, attention, novelty, hyperfocus, emotional states, tiredness and the influence of the consumer environment.
-
17
Part 2 - What Pulls Me In
Examine how attention, novelty and hyperfocus can shape spending, and why different patterns of intense interest or browsing may require different strategies.
-
18
Part 3- Waiting and Changing the Pattern
Explore delayed gratification, the value of creating a pause before purchasing, and ways of making future financial benefits more concrete.
-
19
Bonus — Space Between the Urge and the Purchase: Your Module 3 Toolkit
The aim isn’t to stop wanting things. It’s to create enough space between the urge and the purchase to make a deliberate decision. These worksheets help you track what sets your spending off, work out what your spending gives you, and use practical tools at each stage of the purchase process, from the first trigger to the moment you pay.
-
20
Module 3: Knowledge Check
-
21
Objective for Module 4 – Executive Function and Money
By the end of this module, you’ll be able to see the executive demands hidden in everyday money tasks and match each one with the right support.
-
22
Part 1 - The Hidden Work In Money Tasks
Even simple money tasks, like checking a bank account or paying a bill, are made up of several smaller steps. Each step relies on a different mental skill: planning, organising, remembering to act at the right time, and keeping track of time.
In this part, we break money tasks down to see what they actually ask of us. We look at why intentions often don't turn into action, and why "just remember to do it" so often doesn't work.
-
23
Part 2 - Getting Unstuck
Sometimes we know exactly what needs doing and still put it off. In this part, we look at why money tasks get stuck: avoidance, paperwork, and the mental load of too many decisions or tasks that are too big.
You'll learn to work out what exactly you're avoiding, and to reduce the number of decisions and the size of each task, so that starting asks less of you. We finish by looking at what this means for building a money system that works for you, which is where Module 5 picks up.
-
24
Bonus — Making Money Tasks Ask Less: Your Module 4 Toolkit
A money task that looks simple often hides a lot of work: planning, remembering, starting, deciding and checking. These worksheets help you see that hidden work, find where your tasks get stuck, and make them ask less of you. The aim isn’t to get better at every executive function. It’s to change the task so it fits the way your brain works.
-
25
Module 4 - Knowledge Check
-
26
Objective for Module 5 – Designing a Brain-Friendly Financial System
By the end of this module, you’ll be able to build a financial system that runs on structure and automation rather than memory and willpower.
-
27
Part 1 - Building The System
Instead of relying on yourself to remember and act at exactly the right moment, you can set things up so your money system does some of the work. In this part, we look at the four pillars of a brain-friendly system: automation, how your bank accounts are set up, reminders that arrive when you can act on them, and routines you can turn into habits by linking them to events that already happen.
-
28
Part 2 - Making It Work For You
A system only helps if it fits the person using it. In this part, you'll use if–then plans to keep the system running, adapt it to the way your brain works, and build your own system. Then you'll set up a review loop so the system changes as your life does, and see how the same approach can work for a business.
-
29
Bonus — Practical Tools for Building a System That Works for You
A set of worksheets to help you turn this module into a working money system. Use them to sort what needs automating, a reminder or a routine, set up and name your accounts by purpose, save for goals that feel far away, build cue-based habits, keep track of yearly deadlines, and apply the same system to your business.
-
30
Knowledge Check
-
31
Objective for Module 6 – Flexible Budgeting
By the end of this module, you’ll be able to build a budget that flexes with your income and your capacity, instead of breaking in a hard month.
-
32
Part 1 - How Much Goes Where?
Find out what your money actually needs to cover and how much might reasonably go where. This part covers take-home income (including what it means if you run your own business), starting guidelines for each category, and why most budgets are more optimistic than they should be.
-
33
Part 2 - Budgeting With Your Brain
Most budgeting advice assumes one kind of brain. This part looks at why budgeting can be harder with ADHD, autism or dyslexia, and offers strategies built around how each of those brains actually works.
-
34
Part 3 - When the Numbers Change
Income changes, costs come in lumps, and some months you have less energy than others. This part shows you how to plan for that in advance, including deciding what to protect first, keeping three versions of your budget, and stopping a pay rise from quietly disappearing.
-
35
Bonus - A Budget That Bends: Your Module 6 Toolkit
A budget doesn’t have to be a monthly report card. These worksheets help you see where your money goes now, build a budget that fits the way your brain works, and decide in advance what happens when your income, your costs or your energy change.
-
36
Budget Resources
Bonus Resource Suggestions
-
37
Knowledge Check
-
38
Objective for Module 7 – Debt, Credit and Financial Resilience
By the end of this module, you’ll be able to look at debt without shame, choose a repayment route that fits your brain, and build a buffer for the next shock.
-
39
Part 1 - Debt, Credit and Your Brain
Debt is rarely just about the numbers. This part looks at why debt is so hard to face, how shame keeps you stuck, what can get in the way for ADHD, autistic and dyslexic brains, how credit changes the questions you ask before you buy, and what paying only the minimum really costs.
-
40
Part 2 - Getting Out of Debt
A step-by-step route out of debt: see the whole picture, stop it growing, protect the essentials and choose a repayment strategy that suits you. It also covers what to do when the numbers don't add up, how to contact creditors, where to find safe help, and how business debt is different.
-
41
Part 3 - Building Resilience
Paying off debt isn't the finish line. This part shows you how to redirect what the debt was taking, build a buffer, and plan in advance so that the next financial shock doesn't become new debt.
-
42
Bonus - From Debt to Resilience: Your Module 7 Toolkit
Debt is easier to deal with when you can see it, when the plan runs without you having to remember it, and when you’ve decided in advance what happens next. These worksheets help you take stock of your debt, choose a repayment plan that suits you, contact creditors with confidence, and build enough resilience that the next shock doesn’t become new debt.
-
43
Knowledge Check
-
44
Objective for Module 8 – Earning, Investing and Building Wealth
By the end of this module, you’ll understand how to earn well, invest simply and build long-term wealth, without confusing net worth with self-worth.
-
45
Part 1 - Earning
Income is the starting point, not the whole picture. In this part, we look at what your income really gives you, employment beyond the salary, and self-employment beyond the basics: your real hourly rate, how much depends on one client, and getting paid. We also look at what research says about ADHD, autism, dyslexia and running a business, and how to test a new income stream before committing to it.
-
46
Part 2 - Growing
Saving and investing do different jobs. In this part, we look at risk, return and diversification, what compounding and fees look like in dollars, and why knowing about investing isn’t the same as investing. Then we look at practical ways to invest with an ADHD, autistic or dyslexic brain: checking less often, writing your own rules and keeping choices simple.
-
47
Part 3 - The Long Term
Wealth is what you own, not what you earn. In this part, we look at retirement as future income, how to pay your future self when your income varies, and why it’s never too late to look. We finish with net worth, the three levers of wealth, why wealth isn’t worth, and how to choose one next step that fits where you are now.
-
48
Bonus - From Earning to Wealth: Your Module 8 Toolkit
These tools help you see what your income really gives you, price your time properly if you run a business, test new income ideas before committing to them, write your own investing rules, and track the progress that’s otherwise hard to see.
-
49
Module 8 Knowledge Check
-
50
Objective for Module 9 – Money, Relationships and Life
By the end of this module, you’ll be able to talk about money with the people in your life and make shared decisions that match what your family stands for.
-
51
Part 1 - Deciding What We Stand For
Money is rarely just mine. In this part, we look at why money conversations go sideways when two money stories meet, how to set up a conversation that works for neurodivergent brains, and how to write a Family Constitution: a short document of shared values that makes everyday money decisions easier and more consistent.
-
52
Part 2: Making Decisions That Match
Once we know what we stand for, we still have to make hundreds of small money decisions. In this part, we look at financial boundaries, the Discernment Quadrant for seeing where a decision is coming from, how partners can share money work by strength rather than by default, and how to raise financially capable children, including when both parent and child are neurodivergent.
-
53
Bonus -What We Stand For: Your Module 9 Toolkit
Money is rarely just one person’s business. These tools help you set up money conversations that work for every brain in the room, write your own family constitution, see where your money decisions come from, share money work by strength rather than by default, and set boundaries with the people you love.
-
54
Module 9 Knowledge Check
-
55
Objective for Module 10 – Legacy, Purpose and Financial Freedom
By the end of this module, you’ll be able to define financial freedom on your own terms and start building a legacy in people, not just in money.
-
56
Part 1: Legacy Is Built in People
Legacy isn’t what you leave to the people you love. It’s what you leave in them. In this part, we look at why money conversations need to start early, how to define financial freedom on your own terms, why a legal trust can’t create relational trust, and the three root causes of wealth being lost between generations: no skills, no goals and no ownership.
-
57
Part 2: The Everyday Conversations That Build Legacy
Legacy is built one money moment at a time. In this part, we look at the three everyday conversations that pass values on, what to say (and what not to say) in eight of the most common money moments with children, how to repair when you get it wrong, why generosity is the antidote to entitlement, and how everything in the course comes together in your Personal Financial Blueprint.
-
58
Bonus - What I Leave in Them: Your Module 10 Toolkit
Legacy is built one money moment at a time. These tools help you see where your family is today, have the words ready for the money moments that catch you off guard, write down what you want to pass on, and start giving together.
-
59
Module 10 - Knowledge Check
-
60
Part 1 - Where You Are Now
Modules 1 to 10 explained why money can feel harder for a neurodivergent brain and what you can do about it. This final module is about putting it into practice. You’ll see how much of your Personal Financial Blueprint you’ve already built. You’ll then choose one priority for the next 12 months and learn what helps a change last: tracking what matters, planning for difficult weeks, reviewing once a year and starting again after a break. You’ll also look at what accountability can and can’t do, and how to set up support that works with how you function.
-
61
Part 2 — Making It Last
Starting a change is the easy part. This part looks at what helps change last, how to keep a system going with an ADHD, autistic or dyslexic brain, and how to track, review and start again without starting over.
-
62
Part 3 - Accountability and Your Blueprint
Accountability can help, but it can’t do the whole job. This part looks at what accountability can and can’t do, how to set up support that suits you and your business, and how to ask for what works. It ends with a final check of your blueprint before the capstone.